By Amber Lee
After a 31-year run as a public company, Sotheby’s, which was founded in 1744, announced in June 2019 that it was being acquired by a French billionaire, Patrick Drahi, thus joining its arch-rival auction house Christie’s in conducting business as a privately held company.[1] The privatization of Sotheby’s raised concerns over the loss of transparency in a world that has very little. As a privately held company, the auction house is essentially free of the strict financial reporting mandates imposed by the SEC, which requires public companies to file annual and quarterly reports containing the company’s financial statements.[2]
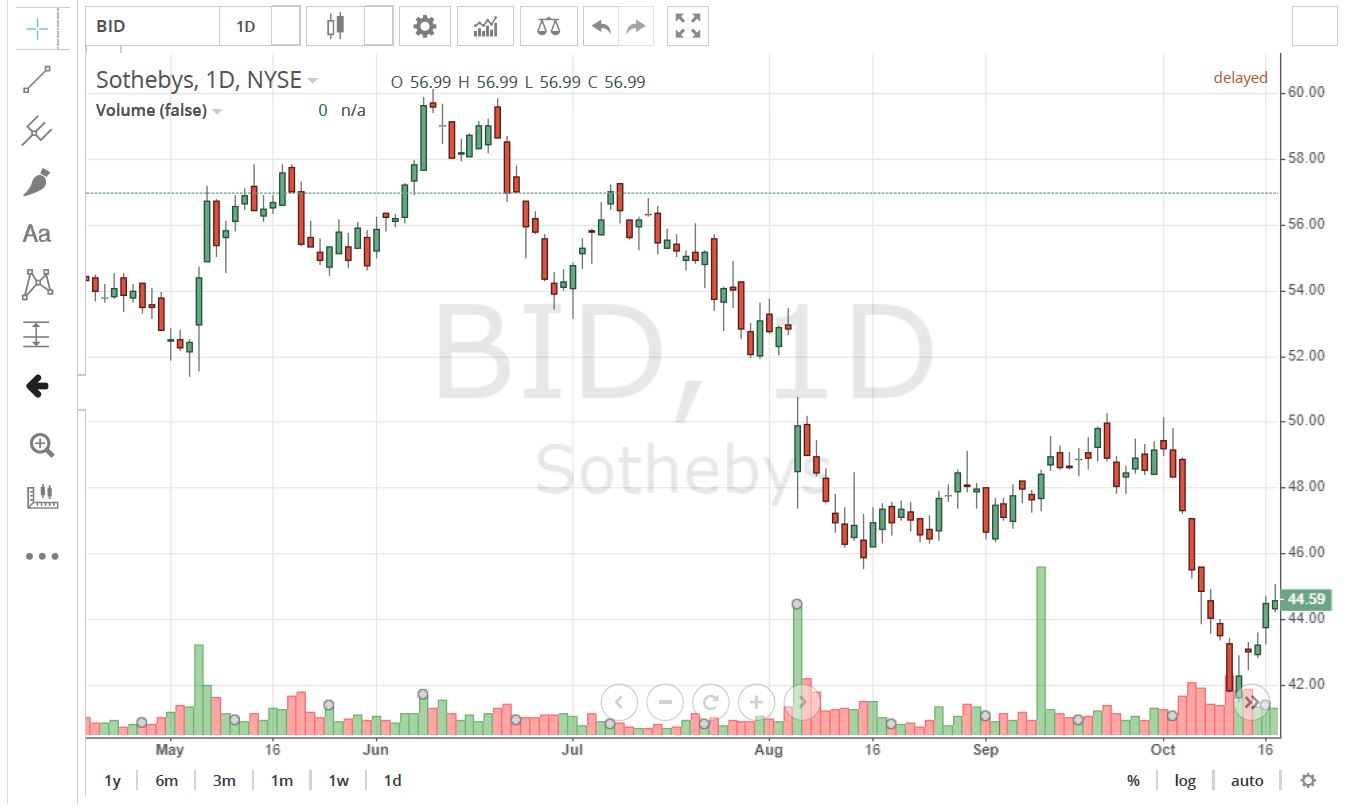
Further, taking Sotheby’s private means it can now avoid the type of public scrutiny on certain auction house practices, such as the use of guarantees (the subject of this article), which could potentially draw unwanted attention to the auction house’s financial health.[3] While spectators were only too happy to have access to annual financial reports (still available here),[4] the financial markets would reflect company performance in spikes and dips of the stock prices. For example, in a statement published in conjunction with the release of its 2018 second quarterly financial report, Sotheby’s attributed the decline in its auction commission margin to the “auction guarantee shortfalls” and “the sale of two guaranteed paintings,” which reduced its auction commission margin by 1.4% and 1.1%.[5] The announcement caused a dip in Sotheby’s stock prices from $52.90 to $49.93 per share. The “sale of two guaranteed paintings” in Sotheby’s statement referred to the sale of a Modigliani and a Picasso, both of which were reported to have been sold to third-party guarantors after sparse bidding.[6] But what exactly is a guarantee, and how does keeping it from public scrutiny help shield an auction house from financial backlash?